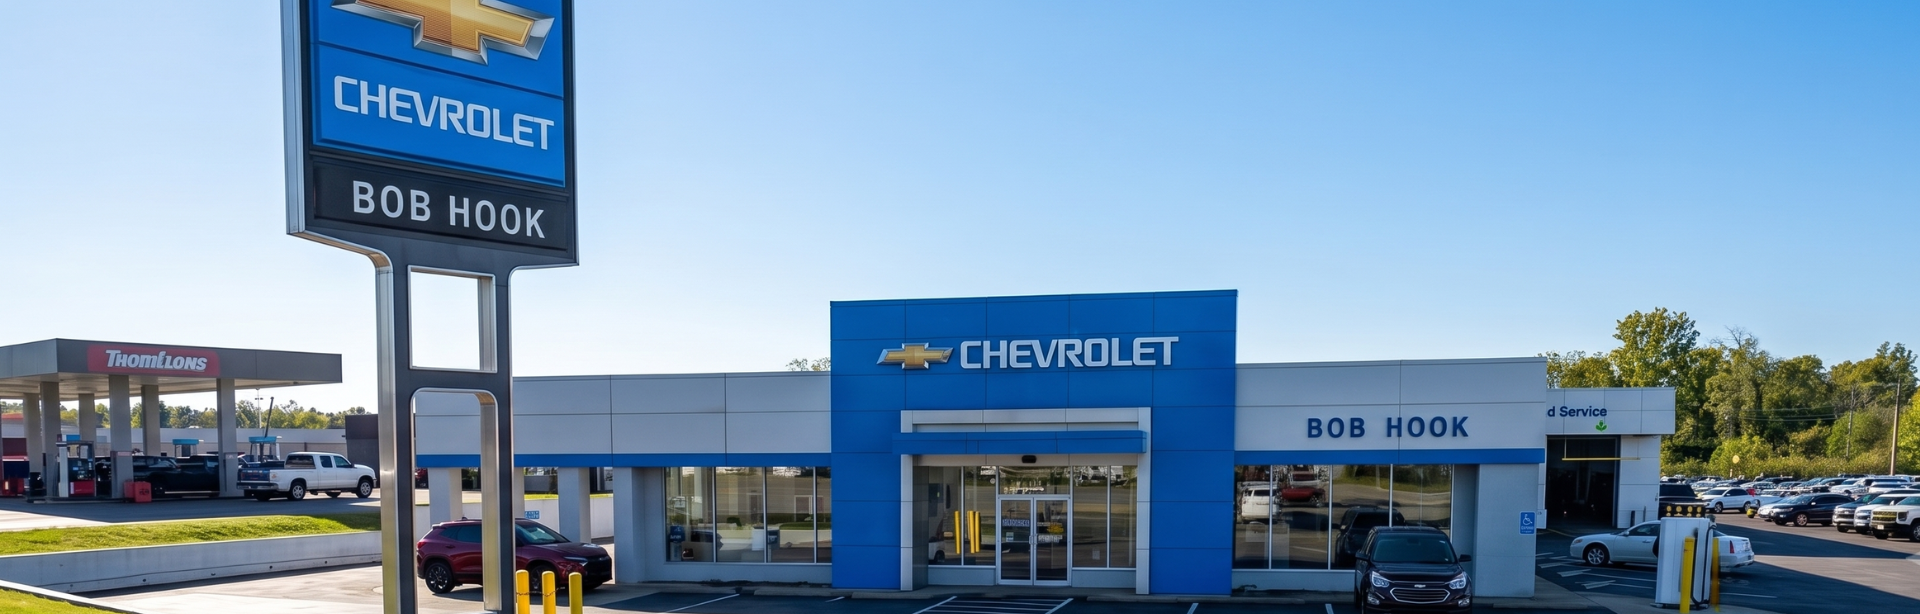

Let's face it-navigating the world of auto loans can sometimes feel more complicated than afternoon traffic on I-264. But securing the keys to a dependable new or pre-owned Chevrolet doesn't have to be a stressful ordeal. As a proud family- and veteran-owned dealership, Bob Hook Chevrolet believes in keeping the financing process completely transparent for drivers all over Louisville, KY. Whether you are commuting daily from Middletown or packing up your vehicle for a weekend picnic at Cherokee Park, you deserve clear answers without any high-pressure tactics.
That is exactly why we put together this straightforward guide. We will walk you step-by-step through the essentials of setting up an auto loan, breaking down the details so there are no surprises along the way. By the time you finish reading, you'll have the practical knowledge needed to confidently finance your next car, truck, or SUV, getting you back to your routine in Jeffersontown with a payment plan that makes sense.
What Should I Know Before Applying for a Car Loan?
Before you start test-driving a new Chevrolet Equinox or Silverado 1500, you need to know two main things: your current credit score and your true monthly budget. For drivers around Louisville, securing favorable financing early means more room in your wallet for weekend trips to Churchill Downs or simply covering the daily commute down I-264. Getting your financial profile organized first gives you the leverage to know exactly what loan terms you can comfortably handle.
The smartest place to begin is by pulling your personal credit report. You are entitled to a free annual copy from the major credit bureaus, and seeing exactly what lenders see prevents surprises at the finance desk. Your credit score directly influences the interest rates available to you. Moving from a "fair" score of around 600 to a "good" score over 670 can significantly lower your Annual Percentage Rate (APR), saving you thousands over the life of the loan. If your numbers are a bit low, you might want to spend a few months paying down existing balances before applying. Many free online credit-education platforms offer great tools for understanding your debt utilization.
Once you know where your credit stands, it is time to map out a realistic budget. It can be tempting to focus solely on the vehicle's monthly payment, but you also need to account for local insurance rates, gas for your specific trim, and routine maintenance. A standard rule of thumb is to keep your total monthly auto expenses below 15 to 20 percent of your take-home pay. Let's look at a quick calculation: if you bring home $4,000 a month, capping your total car costs at $600 to $800 ensures you still have plenty left over for rent in the Highlands or weekend outings at Cherokee Park. Running those numbers through a basic online auto loan calculator lets you test different down payments and terms until you find the perfect sweet spot.
How Do I Get Approved for Chevrolet Financing?
Securing an auto loan shouldn't feel like navigating stop-and-go traffic on I-264. The approval process for a new or certified pre-owned Chevrolet is built to be straightforward and transparent, beginning with a basic credit application. What this means for Louisville drivers is less time dealing with paperwork and a much clearer path to predictable monthly payments.
You can handle these initial steps entirely online from your living room in Saint Matthews, or you can sit down with finance specialists in person. For instance, if you are upgrading to a 2027 Chevrolet Equinox SUV for weekend family outings to Cherokee Park, completing your credit application digitally before you visit can easily save you 30 to 45 minutes at the desk. When you are ready to apply, you will just need to gather a few essential details:
Personal Information: You'll need to supply your full legal name, current residential address, date of birth, and Social Security number so lenders can accurately pull your credit file.
Employment and Income: Financing partners look closely at your debt-to-income (DTI) ratio. Expect to provide your current employer's name, your job title, and your gross monthly income to demonstrate a stable ability to manage the loan.
Vehicle Specifications: Because loan structures depend heavily on the vehicle's value, you will need to specify the exact year, model, and configuration you intend to buy-such as a 2027 Chevrolet Silverado 1500 Gas Truck.
Once your application is submitted, finance experts share your profile with GM Financial alongside a network of trusted local and national lending institutions. These lenders evaluate your FICO credit score, overall income stability, and the total requested amount to determine your eligibility. By casting a wide net, this multi-lender approach helps track down the most competitive interest rates and terms tailored to your unique financial situation, though final approval and specific rates ultimately depend on your credit profile.
What Do Different Loan Terms Mean?

When you get an auto loan offer, the paperwork can be filled with financial jargon. Breaking down the core elements-your interest rate, the length of the agreement, and the money you put down-shows exactly how much a new Chevrolet Equinox LT or Silverado 1500 will cost you over the years. What this means for Louisville drivers is that you can confidently compare different financing options to find a monthly payment that comfortably fits your budget while securing a reliable ride.
APR (Annual Percentage Rate): This figure represents the true yearly cost of borrowing money to purchase your vehicle. Because the APR rolls your standard interest rate and any lender fees into one single percentage, it gives you the most accurate picture of your loan's expense. For example, securing a 5% APR versus an 8% APR on a $30,000 loan drastically changes the amount of interest you'll end up paying by the end of the contract.
Loan Term: Your loan term is the repayment timeline, generally spanning anywhere from 24 to 84 months. Choosing a shorter timeline means your monthly bills will be higher, but you pay far less interest overall. On the flip side, stretching a loan from 60 to 72 months drops your monthly payment, though it increases the total interest paid. If your daily routine involves navigating heavy afternoon traffic on Shelbyville Road near Mall St. Matthews, finding a balanced term ensures you have plenty of room in your budget for both your car payment and routine gas fill-ups.
Down Payment: The down payment is the cash or trade-in equity you apply upfront before financing the remaining balance. Handing over a larger sum immediately reduces the total amount you need to borrow, which directly shrinks your monthly obligation. Whether you're packing up the SUV for a family picnic at Cherokee Park or running daily errands around Jeffersontown, carrying less debt on your vehicle provides greater financial breathing room.
Before signing any paperwork, it's always smart to read through the full offer and ask your finance specialist questions if a specific detail isn't clear. You can also research current trade-in values and long-term ownership costs on trusted resources like Kelley Blue Book to help structure a deal that works for you.
Can I Finance a Pre-Owned Chevrolet?
Absolutely. Securing an auto loan for a pre-owned or Certified Pre-Owned (CPO) Chevrolet is a very common route, and the process is just as straightforward as financing a brand-new model. Whether you are eyeing a used Chevrolet Silverado 1500 to haul equipment out in Shepherdsville or a pre-owned Equinox for weekend errands around Saint Matthews, the paperwork and approval steps closely mirror a new-car purchase. You might assume used car loans come with extra hoops to jump through, but local banks and credit unions handle these applications daily, often turning around approvals in minutes.
Chevrolet CPO vehicles offer distinct advantages that make them especially appealing to both buyers and banks. Before hitting the lot, each of these vehicles must pass a rigorous 172-point inspection conducted by factory-trained technicians. They are also backed by a 12-month/12,000-mile Bumper-to-Bumper Limited Warranty and a 6-year/100,000-mile Powertrain Limited Warranty. What this means for Louisville drivers is serious peace of mind-you get the lower purchase price of a used car along with the dependable safety net usually reserved for new models. Because these vehicles carry less risk of unexpected breakdowns and hold their value remarkably well, lenders often extend competitive interest rates to buyers.
If your daily routine involves navigating afternoon traffic on I-264 or running the kids to practice in Middletown, stepping into a spacious, well-maintained Chevrolet Traverse makes practical and financial sense. Taking the time to research your options ensures you find the right fit for Kentucky's variable weather and your family's lifestyle. To verify market values and read in-depth reviews on specific trims before applying for a loan, trusted resources like Edmunds are excellent places to gather reliable pricing data.
How Does a Trade-In Affect My Auto Loan?
Trading in your older car works exactly like handing over a cash down payment. By applying the value of your current ride directly to the purchase price of your next vehicle, you immediately reduce the total amount you need to borrow. For drivers navigating the daily stop-and-go along Shelbyville Road or loading up for weekend picnics at Cherokee Park, this means lower monthly payments and less total interest paid over the life of your new auto loan.
Let's look at a straightforward hypothetical scenario to see the math in action. Suppose you are looking to purchase a vehicle priced at $30,000, such as a gas-powered Chevrolet Equinox LS. If the trade-in value of your old car is appraised at $5,000, that amount is subtracted straight from the sticker price. You are now only financing $25,000, plus any applicable taxes and state fees. By financing thousands less from the start, your loan terms become far more manageable month to month.
Getting that number pinned down is a hassle-free process. A professional appraisal can typically be completed right on site while you take a new Chevrolet Traverse or Trax out for a test drive. To ensure you feel confident in the valuation, it is always a smart move to cross-check numbers through independent research tools like Consumer Reports, which tracks historical and current automotive pricing trends. Knowing what your car is worth ahead of time ensures a fair, transparent transaction, giving you more buying power for your next Kentucky road trip.
Frequently Asked Questions (FAQs)
How does Bob Hook Chevrolet ensure customers fully understand their vehicle warranties?
Bob Hook Chevrolet's team will review the agreement with you to ensure you have all the information you need before making a decision. Our Bob Hook Advantage program provides clear benefits, including lifetime powertrain warranties, and our staff works alongside you to guarantee every detail of your coverage is completely understood before you leave the lot.
What community organizations does Bob Hook Chevrolet support in the Louisville area?
Bob Hook Chevrolet partners closely with local groups like the YMCA of Greater Louisville and Twisted Pink. The dealership's team frequently organizes school supply drives and charity car shows, earning honors like the BBB Torch Award for Community Involvement and Integrity and reflecting a dedication to the community that has supported this family-owned business since 1953.
How does Bob Hook Chevrolet make the car-buying process convenient for customers?
Bob Hook Chevrolet offers an innovative sales process that allows you to complete your purchase online and arrange for home deliveries. Whether you work with our Spanish-speaking sales staff or enjoy complimentary snacks and beverages in our family-friendly facilities, the dealership provides transparent pricing so your experience is smooth from start to finish.
What credit score is needed for Chevrolet financing?
While there is no official minimum, GM Financial typically looks for prime scores to provide the most competitive rates on a new Chevrolet Equinox or Silverado 1500. Bob Hook Chevrolet's finance team will review your application and work directly with our lender network to help secure strong financing terms, whether you commute from Jeffersontown or Saint Matthews.
Can I get Chevrolet financing with no money down?
Yes, qualified buyers can often secure Chevrolet financing without an initial down payment. Approval generally depends on income and credit history, but Bob Hook Chevrolet will evaluate your situation to find the best path forward. Bringing a down payment is still helpful because it reduces your overall monthly costs for those longer weekend drives out to Churchill Downs or Shepherdsville.
Does Chevrolet have 0% financing in the Louisville area?
GM Financial frequently rolls out promotional 0% APR offers on select new models for well-qualified buyers. Because these special incentives change monthly, Bob Hook Chevrolet will check the latest programs and clearly lay out which current offers apply to your vehicle choice. Our team ensures drivers around Middletown and the Highlands never miss out on available local promotions.